
Growth rate of the corporate loan stock accelerated in summer 2026
The stock of corporate loans at banks operating in Finland grew during summer 2026. Non-financial corporations drew down a large volume of loans in June–August compared with the corresponding period in 2025. Legislation changed (pension reform), and as a result subsidiaries of employee pension institutions can use leverage in their real estate investments more extensively than before, which in part explains why non-financial corporations drew down more loans.
In August 2026, the stock of corporate loans[1] granted by banks operating in Finland stood at EUR 66.3 billion, compared with EUR 62.2 billion in the corresponding period a year earlier. n August 2026, the annual change in the loan stock was 7.2%, as opposed to −0.2% in the corresponding period a year earlier. During the summer, non-financial corporations drew down a large volume of new loans compared with 2025, and the corporate loan stock grew as a result.
In August 2026, non-financial corporations drew down new loans worth EUR 1.4 billion, which is 29% more than in the corresponding period a year earlier. In June–August, non-financial corporations drew down a total of EUR 11.5 billion in new loans, which is 33% more than in summer last year. Growth in corporate loans is in part explained by the pension reform that entered into force in July, which also affects the employee pension system[2]. Subsidiaries of employee pension institutions can use leverage in their real estate investments more extensively than before. In June 2026, too, non-financial corporations drew down a large volume of new loans (EUR 4.0 billion), which was 24% more than in the corresponding period a year earlier.
The average interest rate on new corporate loans rose in August 2026 from a year earlier. The average interest rate on new corporate loans drawn down in August was 4.39%, as opposed to 4.07% a year earlier. The average interest rate on the corporate loan stock was 3.82% in August 2026, compared with 3.57% in the corresponding period a year earlier.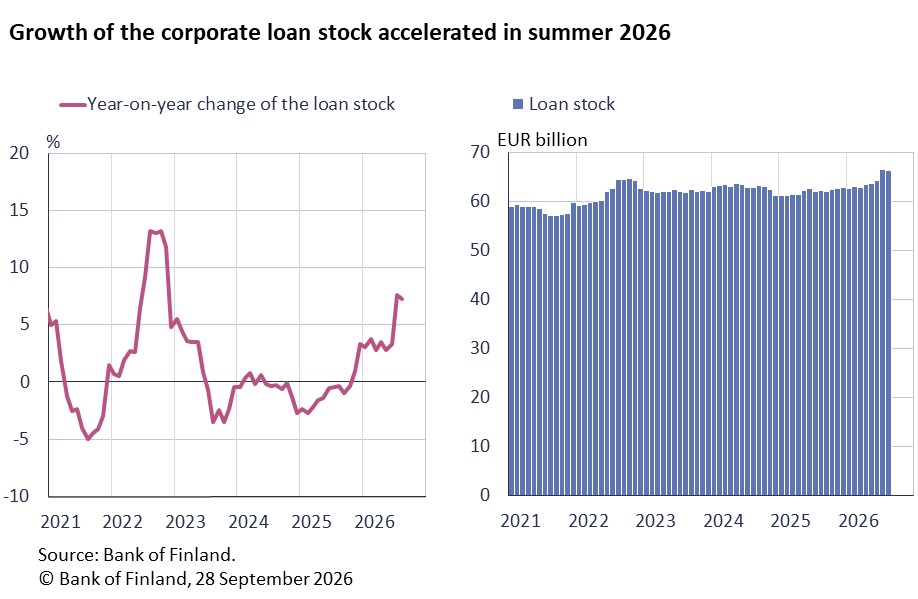
Loans
In August 2026, drawdowns of new housing loans by Finnish households amounted to EUR 1.1 billion, an increase of EUR 20 million compared with the corresponding period a year earlier. Of the newly drawn housing loans, buy-to-let mortgages accounted for EUR 110 million. The average interest rate on new housing loans increased from July to 3.35% in August. At the end of August 2026, the housing loan stock stood at EUR 105.4 billion and its annual growth rate was −0.3%. Buy-to-let mortgages accounted for EUR 9.2 billion of the housing loan stock. At the end of August, Finnish households’ loan stock included EUR 17.4 billion of consumer credit and EUR 18.0 billion of other loans.
Finnish non-financial corporations (incl. housing corporations) drew down new loans[3] worth EUR 1.8 billion in August, including EUR 440 million of loans to housing corporations. The pension reform also affected new loan drawdowns by housing corporations and the growth rate of the loan stock. The average interest rate on these new corporate loan drawdowns rose from July and stood at 4.21%. At the end of August, the stock of loans granted to Finnish non-financial corporations totalled EUR 113.3 billion, including EUR 47.0 billion of loans to housing corporations.
Deposits
At the end of August 2026, the total stock of Finnish households’ deposits was EUR 117.8 billion, with an average interest rate of 0.90%. Overnight deposits accounted for EUR 71.7 billion and deposits with an agreed maturity for EUR 17.4 billion of the total deposit stock. In August, Finnish households concluded new agreements on deposits with an agreed maturity worth EUR 1.3 billion. The average interest rate on new deposits with an agreed maturity was 2.57% in August.
Loans and deposits to Finland, preliminary data |
|||||
| June, EUR million | July, EUR million | August, EUR million | August, 12-month change1, % | Average interest rate, % | |
| Loans to households, stock | 140,654 | 140,658 | 140,838 | 0.2 | 3.57 |
| - of which housing loans | 105,396 | 105,410 | 105,420 | -0.3 | 3.04 |
| - of which buy-to-let mortgages | 9,193 | 9,213 | 9,233 | 3.15 | |
| Loans to non-financial corporations2, stock | 110,779 | 113,245 | 113,302 | 5.4 | 3.58 |
| Deposits by households, stock | 118,120 | 118,0 | 117,762 | 2.0 | 0.90 |
| Households' new drawdowns of housing loans | 1,290 | 1,197 | 1,131 | 3.35 | |
| - of which buy-to-let mortgages | 112 | 120 | 112 | 3.48 | |
* Includes loans and deposits in all currencies to residents in Finland. The statistical releases of the Bank of Finland up to January 2021, as well as those of the ECB, present loans and deposits in euro to euro area residents and also include non-profit institutions serving households. For these reasons, the figures in this table differ from those in the aforementioned releases.
1 Rate of change has been calculated from monthly differences in levels adjusted for classification and other revaluation changes.
2 Non-financial corporations also include housing corporations.
- Euro-denominated deposits and loans of euro area residents: stock, 12 month rate of change and average interest rate
- Euro-denominated loans and deposits of Finnish households
- New business on loans and new drawdowns of household loans
- Finnish contribution to the euro area monetary aggregates and their main counterparts
- Imputed interest rate margins on loans from MFIs
The next news release on money and banking statistics will be published at 10:00 on 28 October 2026.
Related statistical data and graphs are also available on the Bank of Finland website: https://www.suomenpankki.fi/en/statistics/.
[1] Excluding housing corporations.
[2] Government proposal 40/2026 vp | Parliamentary matters | Parliament.
[3] Excluding overdrafts and credit card credit.